

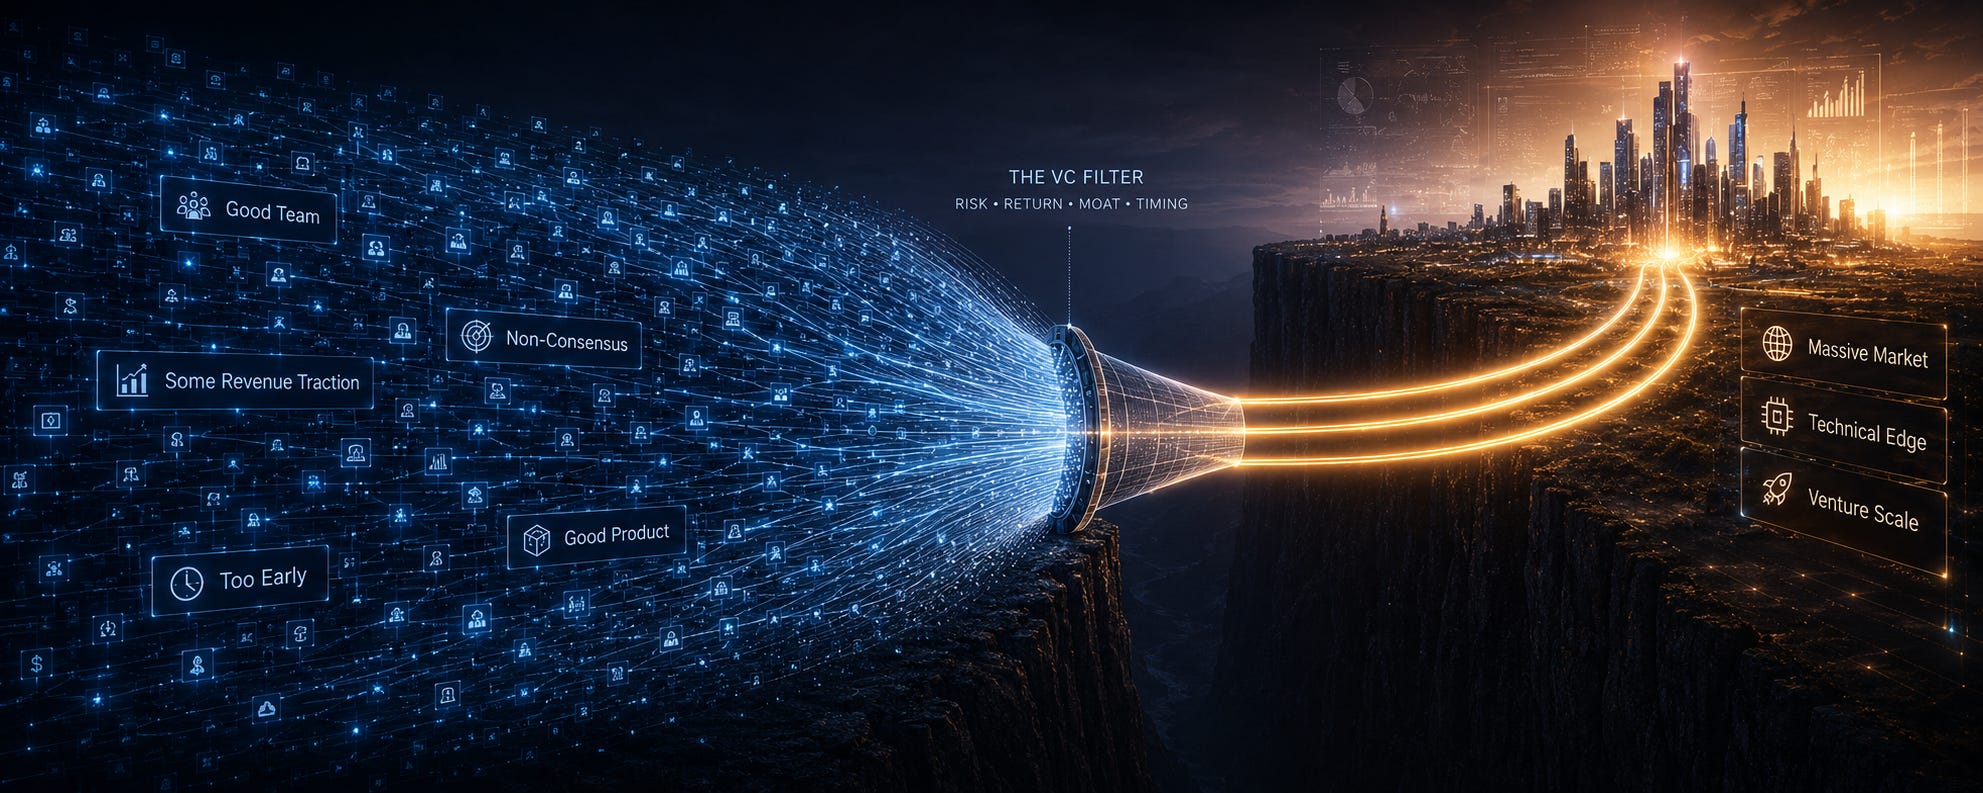
We are currently seeing one of the biggest bifurcations in early-stage startup funding I can remember.
Over the last few weeks, I’ve had dozens of conversations with founders, VCs and family offices about what is actually “fundable” right now. The consistent takeaway is that there is no shortage of capital. There is a shortage of companies investors believe deserve venture-scale capital.

The headline funding numbers make the market look incredibly healthy. Global startup funding hit a record $510 billion in the first half of 2026, already exceeding the $440 billion invested during all of 2025. But OpenAI and Anthropic alone accounted for $217 billion, or 43% of the entire market.
In the U.S., the concentration is even more extreme. Roughly 73% of venture dollars this year have gone into billion-dollar-plus rounds, while PitchBook found that just five deals represented 73% of all U.S. venture investment in Q1.
That distortion is now happening at the earliest stages too.
More than 40% of seed and Series A investment globally in early 2026 went into $100M+ rounds, and in the U.S. it was more than half. Carta says the 95th percentile seed valuation hit $200.4 million in Q2, versus $72.2 million just one year earlier. That is a 177% increase in twelve months.
At the same time, the traditional startup fundraising market is getting harder.
Carta saw roughly the same amount of pre-seed capital deployed in Q2 as a year ago, $3.19 billion versus $3.22 billion, but spread across 11,500 instruments instead of 14,825, a roughly 22% decline in deal volume.
Crunchbase found that sub-$5 million U.S. seed deals fell roughly 20% year over year, while the part of the market that actually grew was rounds of $10 million or more.
This is the bifurcation.
On one side, investors are willing to fund the companies they believe can become category-defining businesses with enormous amounts of capital, increasingly at valuations and round sizes that would have looked like Series B or Series C financing only a few years ago.
On the other side are thousands of legitimately good startups with customers, revenue, solid products and respectable growth that are discovering those attributes alone are no longer enough.
Even the benchmarks have moved. The median U.S. seed round reached roughly $3 million last year, 3x its 2018 level, while the median Series A reached $15 million and continued moving higher in 2026. More importantly, investors interviewed by Crunchbase described the old ~$1 million ARR Series A benchmark migrating toward $2 million, $3 million or even $4 million ARR, depending on growth and category.
So the middle is getting squeezed.
A company can have $3 million of revenue, grow 50% or 70%, generate attractive margins and ultimately become a fantastic $100 million or $300 million business.
That does not necessarily make it a venture business anymore.
The venture model mathematically needs outliers. As more capital concentrates into the perceived winners, investors are increasingly underwriting around some combination of exceptional speed, enormous market size, technical differentiation, founder quality and the possibility of a multi-billion-dollar outcome.
The paradox is that it has arguably never been cheaper or easier to build a software company, while simultaneously becoming harder to convince institutional investors that the company needs venture capital.
That distinction matters.
Founders should not interpret a difficult fundraising environment as meaning their company is bad. They should ask a different question:
Is this a good business, or is this a venture-scale business?
Those used to overlap much more frequently.
In 2026, they are becoming two increasingly different things.
Capital has not disappeared.
The definition of what deserves venture capital is getting much narrower.
More from Value Add VC
A few other things worth reading from Value Add Pulse, where I track startup funding, AI, IPOs and the deals shaping the venture market.
What $67B in AI Buyouts Says About Where Value Is Moving
Stripe’s $7.5B OpenRouter deal and SpaceX’s $60B Anysphere acquisition show how aggressively strategic value is shifting toward AI distribution, infrastructure and proprietary usage data.
Read the analysis →
Rillet Hits a $1B Valuation After Just Two Years
The AI-native accounting company raised a $100M Series C, its third funding round in a year, pushing total capital raised above $200M. It is a perfect example of the other side of today’s venture bifurcation.
Read more →
Nvidia’s Moat Is Moving From Silicon to Its Balance Sheet
With $48.5B of quarterly free cash flow, a $500B GPU financing pact and billions invested across the AI ecosystem, Nvidia is increasingly using capital itself as a competitive advantage.
Read the breakdown →
Unitree Robotics Jumped 629% in Its Public Debut
The humanoid robotics company briefly reached a $66B valuation after listing in Shanghai, giving public markets one of their first major price-discovery moments for humanoid robotics.
Read more →
Value Add Pulse is updated throughout the day with the startup, VC, AI and public-market news I think is actually worth paying attention to.